Lunch near you.
Search for lunch places by town, address or your location. The maximum value of the lunch benefit is 14,00 € and the taxable value at least 8,80 € per working day in 2026.
Search for lunch places by town, address or your location. You can see the distance, opening hours and a link to the lunch menu.
- Lunch seekers: nearest lunch places and tax on the lunch benefit
- Employers and restaurants: lunch benefit, VAT 13.5% and obligations
Where to have lunch today?
Enter a town or address, or locate yourself. You will see the nearest lunch places by distance and opening hours.
Today's lunches from restaurants
All lunch places
Lunch by city: Helsinki · Espoo · Tampere · Vantaa · Oulu · Turku · Jyväskylä · Kuopio · Lahti · Pori · Joensuu · Lappeenranta · Hämeenlinna · Vaasa · Seinäjoki · Rovaniemi · Kotka · Salo · Mikkeli · Kouvola
Geodata © OpenStreetMap contributors (ODbL). Check the daily lunch menu and price on the restaurant's own website.
Today's lunch menus
Choose a town or city and the links open directly to its lunch menus.
Post today's lunch
Enter the week's lunches all at once. They appear first in Lunch Radar when someone searches for lunch in your town. Listing is free of charge.
Calculator
Calculator
Calculators on their own pages: Lunch benefit calculator · Lunch benefit cost calculator for businesses · All calculators
Lunch Radar in figures
Taxable values of the meal benefit 2025 and 2026
The cash values of the meal benefit (lunch benefit) confirmed annually by the Finnish Tax Administration. The 75 per cent rule applies to lunch vouchers and targeted payment instruments (card, mobile) when the value of the benefit is at most the upper limit. The 2027 values had not been published on 6.10.2026.
| Instalment | 2025 | 2026 |
|---|---|---|
| Value of the meal benefit, general rule | 8,60 € | 8,80 € |
| Meal cost range in which the general rule is used | 8,60–13,70 € | 8,80–14,00 € |
| Maximum value of a lunch voucher or payment instrument per working day | 13,70 € | 14,00 € |
| Taxable value of a voucher or means of payment | 75% of face value, at least €8.60 | 75% of face value, at least €8.80 |
| Hospital, school or daycare staff | 6,45 € | 6,60 € |
| Supervision of pupils or those in care during meals | 5,16 € | 5,28 € |
| Hotel and restaurant sector staff and airline personnel | 7,31 € | 7,48 € |
Median lunch price by city 6.10.2026
Lounasaika.fi calculates the median price from restaurants' own lunch menus every weekday morning. The figure describes the restaurants included in the service on one day, not all restaurants in the whole city; it may also include, for example, soups and café lunches. An official, published nationwide lunch price index was not found.
| City | Median price | Restaurants in the calculation |
|---|---|---|
| Oulu | 13,60 € | 40 |
| Helsinki | 13,50 € | 171 |
| Tampere | 13,50 € | 81 |
| Vantaa | 13,30 € | 52 |
| Lahti | 13,30 € | 41 |
| Espoo | 13,15 € | 50 |
| Jyväskylä | 13,00 € | 35 |
| Turku | 12,00 € | 54 |
| Kuopio | 11,35 € | 30 |
Source: Lounasaika.fi, lunch price statistics by city (retrieved 6.10.2026)
Where the lunch benefit can be used in 2026
According to the Finnish Tax Administration's guidance, a lunch voucher or a benefit loaded onto a card or mobile is valued at 75 % only if it can be used solely to pay for meals and their delivery. The conditions apply to a lunch benefit with a face value of at most 14,00 €.
| Purpose of use | Does the lunch benefit work? | Condition or note |
|---|---|---|
| Restaurant lunch on the premises | Yes | One meal per domestic working day |
| A meal ordered from a restaurant to home or the workplace | Yes | The cost of transporting a meal may be paid with the same means of payment |
| Take-away meal from a shop's service counter | Yes | Ready to eat as is, e.g. salads, filled baguettes and hot meals prepared by the shop itself |
| Industrially produced ready meals and convenience foods | No | According to the guidance, the payment instrument cannot be used to pay for ready meals |
| Drinks only | No | Drinks cannot be bought with a lunch benefit |
| Currency exchange, cash or change | No | The means of payment must not be convertible into cash |
| Holiday days and days off | Not at the 75% value | Benefits granted for holiday and rest-day periods are valued at their nominal value |
Food waste in catering services
The Natural Resources Institute Finland's 2018–2019 measurement of professional kitchens and restaurants. The shares are percentages of food prepared and grams per customer. No more recent nationwide figure for catering services was found on 6.10.2026.
| Instalment | Share of prepared food | Grams per customer |
|---|---|---|
| Total food waste | 15,9 % | 89 g |
| Catering waste (left over from the serving line or buffet) | 9,1 % | 51 g |
| Plate leftovers | 5,4 % | 30 g |
| Kitchen food waste | 1,5 % | – |
| Food waste nationwide per year | 61 million kg (11 kg/inhabitant) | – |
| Food waste nationwide per year (incl. inedible parts) | 78 million kg (14 kg/inhabitant) | – |
Save time with ready-made templates
Free tool available to download with a free account. Larger tools as a one-off purchase, no subscription: files immediately after payment.
 Free tool
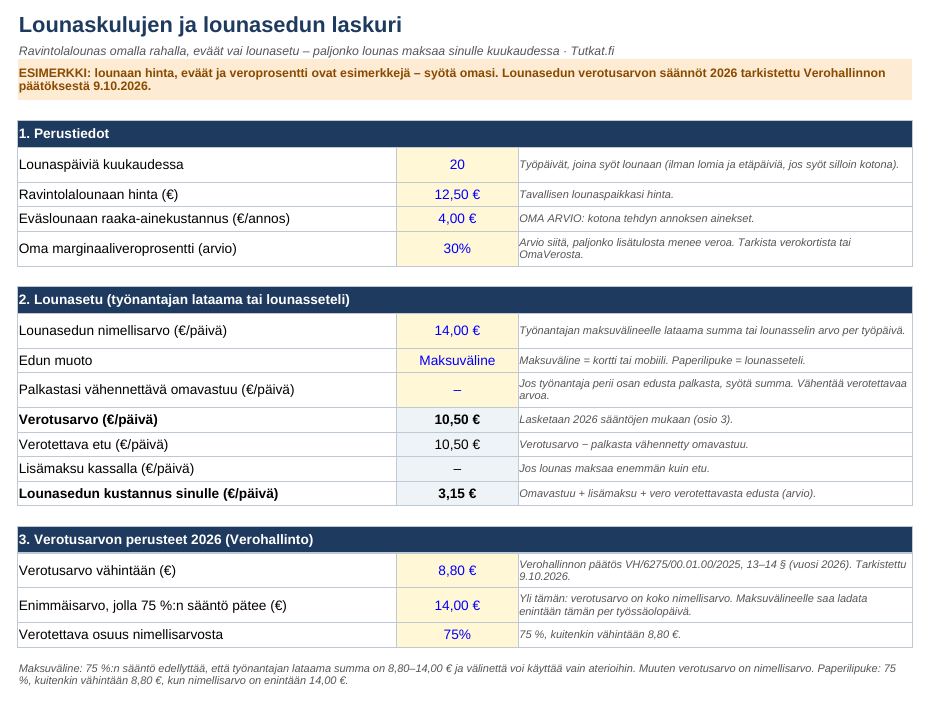
Calculator for lunch costs and the lunch benefit
Compare the real price to you per month and per year of a restaurant lunch, a packed lunch and the lunch benefit.
- Restaurant lunch, packed lunch and lunch benefit side by side
- Taxable value of the lunch benefit 2026 (8,80 € / 14,00 € / 75 %)
- Deductible, extra charge at checkout and tax estimate
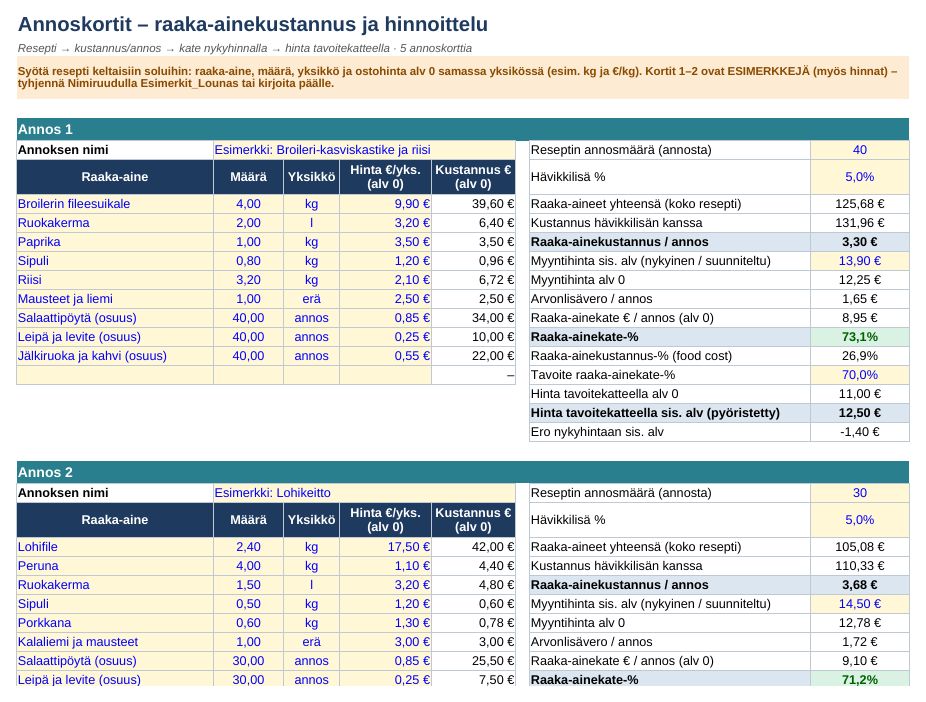
Lunch restaurant margin and pricing calculator
Portion cost, margin %, pricing and daily sales tracking.
Lunch and restaurant entrepreneurs
9,90 € + VAT 25,5 % = 12,42 €Buy 9,90 € + VAT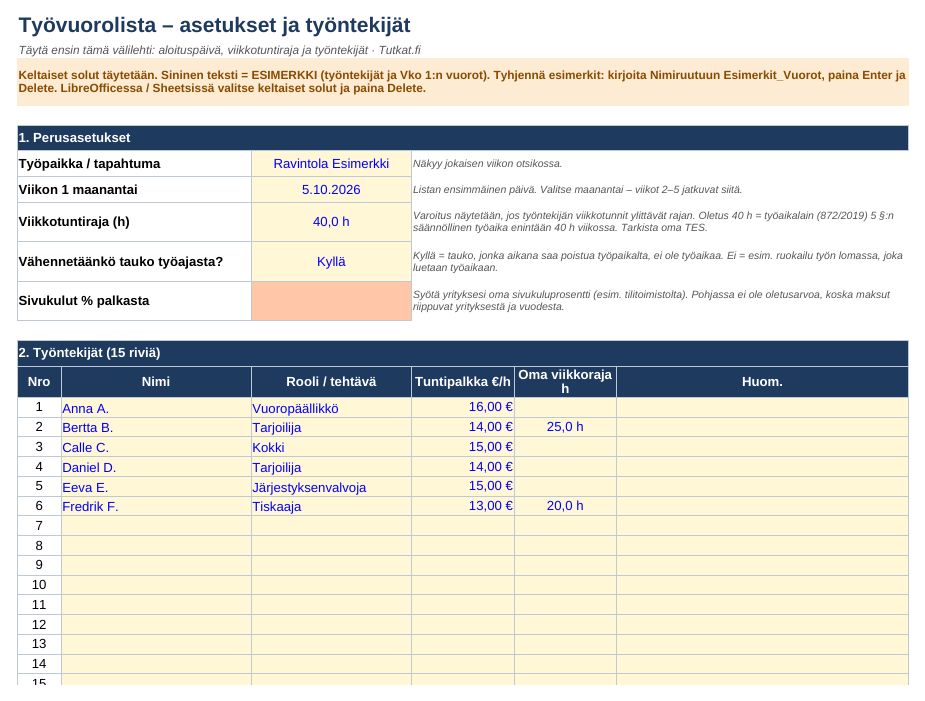
Shift schedule and hours calculator
Shifts for 15 employees, hours across midnight, weekly limit warning and payroll cost.
Restaurants, shops and events
4,90 € + VAT 25,5 % = 6,15 €Buy 4,90 € + VATEntrepreneur Package: all 10 tools €29 + VAT (separately €109 + VAT) →
Read before you decide
Lunch benefit 2026: taxable value, maximum amount and use
The maximum value of the lunch benefit is 14,00 € and the taxable value at least 8,80 € in 2026. See examples, usage rules and what lunch costs now.
Read the guide →Setting up a lunch restaurant: notifications, permits and costs
What starting a lunch restaurant requires: food premises notification, hygiene passports, alcohol licence, VAT and displayed prices. Checklist and deadlines.
Read the guide →Featured
Deadlines and dates
Lunch Radar reminds its subscribers by email.
- Last day to use paper Lounari and Virike vouchers
Edenred's paper lunch and Virike vouchers are valid as a means of payment until the end of 2026. New vouchers were last sold on 31.5.2026; in future the benefit will be provided on a card or in a mobile app.
Source
No upcoming dates right now.
Frequently asked questions: Lunch Radar
How much tax do I pay on a lunch benefit in 2026?
The taxable value of a lunch voucher or of a lunch benefit loaded on a card or mobile is 75 % of the value of the benefit, but at least 8,80 €. For example, for a 14,00 € benefit the taxable value is 10,50 €. The employer often deducts this amount from the net pay, in which case no taxable benefit arises (Finnish Tax Administration).
What is the maximum value of the lunch benefit in 2026?
14,00 € per working day (13,70 € in 2025). The lowest value at which the 75 per cent rule applies is 8,80 €. If lunch costs more than your benefit, you pay the difference yourself (Finnish Tax Administration decision VH/6275/00.01.00/2025).
How much does lunch cost?
The median price calculated from Lounasaika.fi lunch menus on 6.10.2026 was 13,50 € in Helsinki and Tampere, 13,60 € in Oulu, 12,00 € in Turku and 11,35 € in Kuopio. No official nationwide lunch price index has been published; according to Statistics Finland's price index, restaurant and catering prices rose by 1,9 % year on year in August 2026.
Did lunch VAT fall in 2026?
Yes. The VAT on restaurant and catering services fell from 14 per cent to 13.5 per cent from 1.1.2026. The VAT on serving alcoholic drinks is still 25.5%. A half-percentage-point cut corresponds to about 6 cents on a €13.50 lunch, if it passes fully into the price (Finnish Tax Administration).
How much does a lunch benefit cost the employer?
When the employee pays the taxable value of the benefit (75 %, at least €8.80) from their net pay, the employer's share of a €14.00 benefit is at most €3.50 per working day. If the employee pays at least the taxable value, according to the Tax Administration no taxable benefit arises.
Are side costs paid on the lunch benefit?
According to the Finnish Tax Administration, a taxable meal benefit is wages, so the employer pays the health insurance contribution on its value and the employee pays the medical care and daily allowance contribution. If the employee pays at least the taxable value of the benefit themselves, no taxable benefit arises. Check the treatment of other payroll side costs with payroll or the pension insurance company.
How must a restaurant provide allergen information?
A restaurant must disclose all substances causing allergies and intolerances used in preparing the food (14 groups, EU Regulation 1169/2011). The information may be given orally if it is clearly announced near the food, for example on a board or leaflet (Finnish Food Authority).
Where must a restaurant's Oiva report and prices be displayed?
The latest Oiva report must be displayed at the entrance or in another easily noticeable place and on the website (Finnish Food Authority). The price list for services must be displayed on the premises and on the website, if possible also visible from outside, and prices are stated as total prices including taxes (FCCPA, Price Marking Decree 553/2013).
Can you order food home or from a food delivery service with the lunch benefit?
Yes, provided the payment instrument can be used only for meals and their delivery. According to the Finnish Tax Administration's guidance, the 75 per cent taxable value applies when the benefit can be used solely for meals and the costs of delivering a meal, for example home delivery. One meal per working day.
Can you buy food from a shop with the lunch benefit?
Only ready-made take-away meals that are ready to eat as they are, such as deli-counter salads, filled baguettes and hot dishes prepared by the shop itself. Industrially made ready meals, convenience foods and drinks cannot be paid for with a lunch benefit (Finnish Tax Administration, Fringe benefits in taxation).
How much does a student lunch cost?
From 1.1.2026, a university student pays at most €3.10 (previously €2.95) for a basic meal after Kela's €2.80 meal subsidy has been deducted. The price of special meals for a student is €4.50–5.90 (Kela 30.12.2025).
How is a staff restaurant meal taxed for the employee?
In 2026 the value of a meal arranged by the employer is €8.80 if the employer's direct costs are €8.80–14.00. If the costs are below €8.80 or exceed €14.00, the value is the amount of the costs. For hospital, school and daycare staff the value is €6.60, and for hotel and restaurant staff €7.48 (Finnish Tax Administration decision VH/6275/00.01.00/2025).
Does the employer have to pay VAT on a lunch offered to staff?
When a VAT-liable employer provides a meal free of charge, 13.5 % self-supply tax is payable on it. For a purchased meal the tax base is the purchase price; for a self-produced one, the direct costs plus 22 % for indirect costs. There is no right to deduct VAT on the purchase of lunch vouchers, and no tax is payable on giving them to the employee (Finnish Tax Administration 8.1.2026, KHO 2025:46).
How much food waste do restaurants generate?
In the Natural Resources Institute Finland's measurement in 2018–2019, 15,9 % of the food prepared in catering services went uneaten, or on average 89 g per customer. Most of it was serving waste (9,1 %). Nationwide, food waste in catering services was about 61 million kilograms a year (Luke, study 1/2020).
How to use the information
- Check whether your lunch benefit is €14.00. If the lunch costs more, you pay the difference yourself with another payment method.
- The lunch benefit is intended for working days: according to the Finnish Tax Administration, one meal is given per working day in Finland. Vouchers given for holidays and days off are valued at their face value for tax purposes.
- If you have paper Lounari vouchers, use them by 31.12.2026. After that they are no longer valid as a means of payment.
- With a lunch benefit you can also pay for a meal ordered from a restaurant for delivery to your home or workplace, including the delivery, and for a ready meal from a shop's service counter, but not for convenience foods or drinks alone.
- Student: from 1.1.2026, a higher education student's basic meal costs at most €3.10 after Kela's meal subsidy has been deducted. Carry your student card with you.
- Do not hesitate to ask about allergens. A restaurant must disclose all substances from the 14 allergen groups in the food, either in writing or orally, if oral information is clearly indicated as available.
- Check the restaurant's Oiva report at the door, on its website or on oivahymy.fi before choosing a regular lunch spot.
- Employer: when the employee pays from their net salary at least the taxable value of the benefit (75% or at least €8.80), no taxable benefit arises. The employer's share is at most €3.50 of a €14 benefit.
- An employer with its own or outsourced staff restaurant: calculate the direct costs of the meal (raw materials and the wages of preparation and serving staff including statutory social costs). If they are €8.80–14.00, the value of the benefit is €8.80; if the cost exceeds €14.00, the value is the whole cost.
- Restaurant: keep the lunch price visible on the premises and on the website as a total price including tax, and check that VAT on lunch is 13.5 % but 25.5 % on alcoholic beverages.
- Restaurant: track serving waste from the buffet separately. In the Natural Resources Institute Finland's measurement, serving waste was 9.1 % of the food prepared, i.e. more than plate waste (5.4 %) and kitchen waste (1.5 %) combined.
- Restaurant: if you donate surplus food, agree on the cold chain with the distributor. According to the Finnish Food Authority, food intended for food aid can be frozen, but no longer after the use-by date, and the freezing date must be marked.
Useful links
Get the Lunch Radar digest by email
Every Monday or once a month: the most important figures and the next deadlines. Free of charge, and you can cancel at any time.
Related radars
Sources (19)
- Finnish Tax Administration: Decision on the calculation bases of fringe benefits applied in taxation for 2026 (VH/6275/00.01.00/2025, 13.11.2025)
- Finnish Tax Administration: Decision on the calculation bases of fringe benefits applied in taxation for 2025 (VH/6565/00.01.00/2024)
- Finnish Tax Administration: Fringe benefits in taxation (VH/6801/00.01.00/2025, in force from 1.1.2026)
- Finnish Tax Administration: Tax mail goes electronic, home office deduction abolished and gift tax threshold rises (press release 15.12.2025)
- Finnish Tax Administration: Rates of VAT (updated 1.1.2026)
- Finnish Tax Administration: On VAT on staff catering (VH/6225/00.01.00/2025, 8.1.2026)
- Finnish Government: Proposal to reduce value added tax (19.6.2025)
- Eurostat: HICP – ECOICOP ver. 2, Finland, food and beverage serving services (CP111), annual change
- Statistics Finland: Inflation 2.2% in August 2026 (14.9.2026)
- Lounasaika.fi: Lunch prices by city (retrieved 6.10.2026)
- Edenred: Lunch and Virike vouchers will be discontinued in 2026
- Finnish Food Authority: Substances causing allergies and intolerances (updated 20.5.2026)
- Finnish Food Authority: Unpackaged foodstuffs
- Finnish Food Authority: Displaying the Oiva report
- Finnish Competition and Consumer Authority: Indicating the price of goods and services
- Kela: Student meal pricing
- Kela: Higher education students will pay more for a student meal in future (30.12.2025)
- Natural Resources Institute Finland, Restaurant Forum: Food waste in catering services (Natural Resources and Bioeconomy Studies 1/2020)
- Finnish Food Authority: Food aid and surplus food (updated 5.9.2023)
The information has been compiled from public sources on 6.10.2026. Always check the current terms from the original source. The information is not investment, loan or legal advice.